
Books, payday, and the return
Certified Public Accountant Austin Alternative
We keep the books, set up payroll, and write the return, and Steven Palmieri, a Tax CFO, the Entrepreneur's CFO, files the sales-tax receipt, the school bill, and the May report from that same closed month.
When the month is closed
A month is closed when the bank and the books name the same cash.
Click to see a closed month ›Tap to see a closed month ›Close the month
The report follows that month.
Click to see how a month closes ›Tap to see how a month closes ›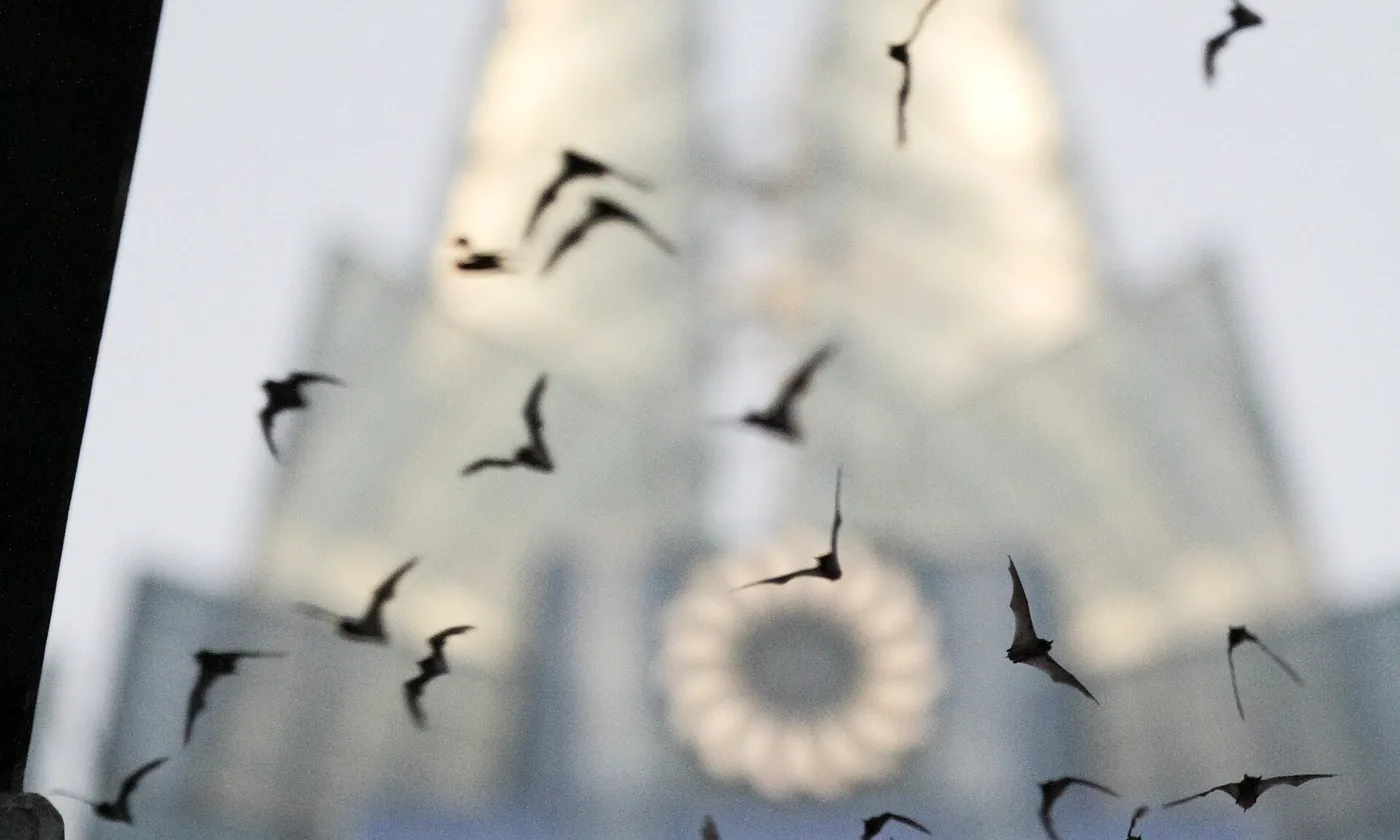
Name the morning deposits
The Ann Richards bridge holds a maternity colony that streams out at dusk from midsummer into fall, and we are all Texans, so we know that flight, and we still name the next morning's deposits before the month is called finished.
Click to see the morning deposits ›Tap to see the morning deposits ›Set up payday
Wages land in the month you approve.
Click to see payday setup ›Tap to see payday setup ›Sort Monday's card batch
The Longhorns have played in that stadium since 1924, and we still sort Monday's card batch into the categories that Saturday earned.
Click to see Monday's batch ›Tap to see Monday's batch ›Count Saturday's sales
Franklin Barbecue has kept a line on East 11th since 2009, and we count a Saturday that long into the week's sales before we close.
Click to see Saturday's sales ›Tap to see Saturday's sales ›Six months that move a year in Austin
Open one month
Open one month. Under the name is the filing that usually lands then, and we watch that date with you.
1January
January's estimates should be built from the months already closed this year, instead of quartering whatever the bill was last April.
Steven and his team watch that date with you, and the number goes out only after those months agree with the bank.
2March
A month left open in the prior year can still be finished before the return is assembled.
That month stays unfinished while the bank and the books still disagree about cash.
3April
April's return uses only months that already agreed with the bank, so the figures are ones you have already read.
We prepare that return, and you sign it after you have seen the year in those months.
4May
The franchise report lands on 15 May, and for report years 2026 and 2027 the Comptroller's no-tax-due line sits at 2,650,000 dollars.
May's figures come from a year that has already been tied to the bank. On the franchise form the 0.375 percent margin covers retail activity and wholesale activity. Every other activity on that form is 0.75 percent.
5July
Halfway through the year we look at cash, at the estimates already sent, and at whether payday still matches the service.
You and we look at July together by video, because July will not sit still until April.
6October
October is when a year can still be moved, while there is time to choose before December locks the numbers.
We use that month for the choices that are still open, not for a reconstruction of the spring.
The dome and the May report
The May report
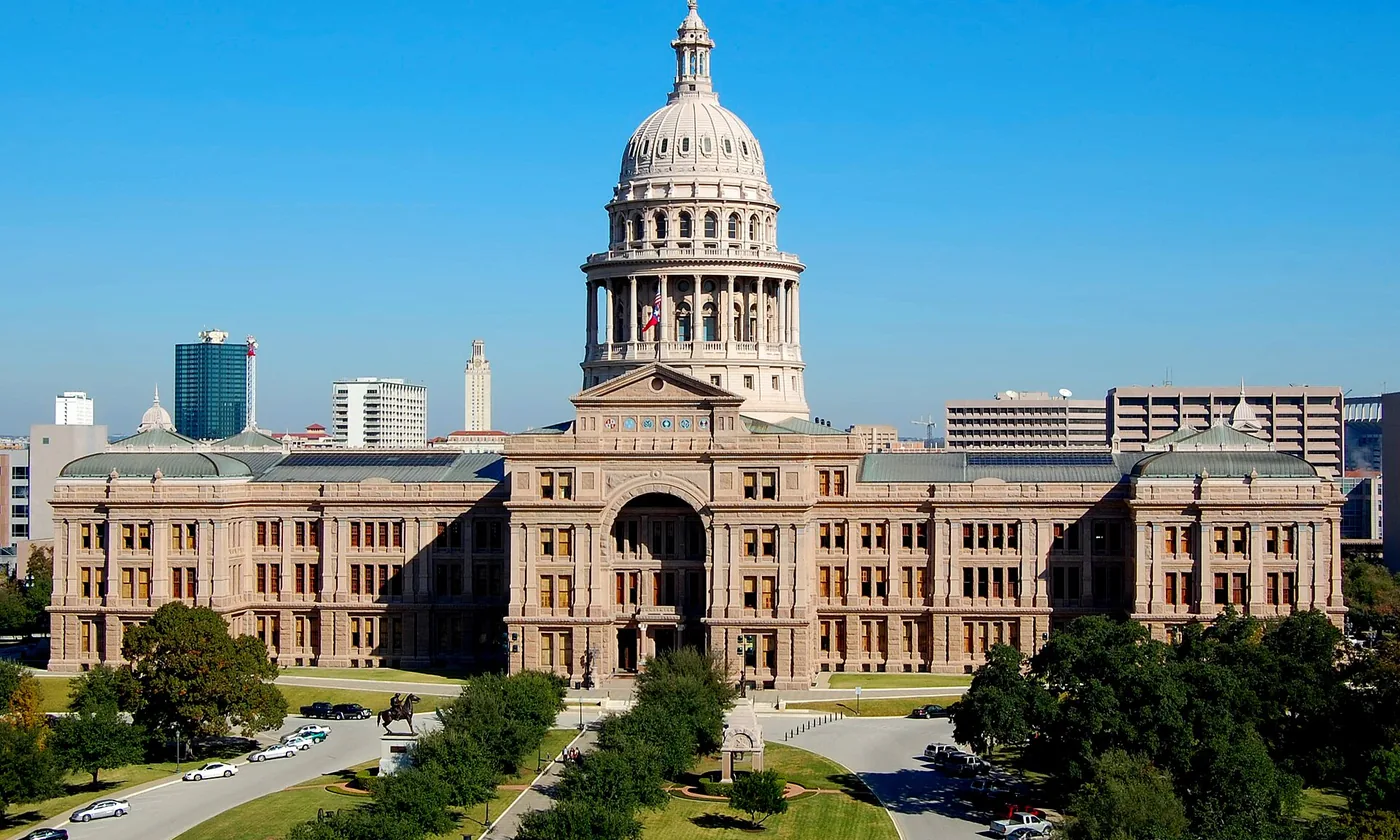
The pink granite capitol went up between 1882 and 1888, and Texans can picture that dome without a tour. We see it and think of the May report that state still expects, filed from a year that already matches the bank.

Steven Palmieri, a Tax CFO, the Entrepreneur's CFO, and his team keep the books, set up payday, and write the return from months that already match the bank.
Tell us which month is open.
Which month matched
Tell us which month last matched the bank, and whether wages already run on your service.
Send the month you last trusted.
You will be talking to the Steven Palmieri practice.
Months, payday, and the return
Months tied to the bank.
Payday on your service.
A return from those months.
What the first screen keeps
The sales-tax receipt, the school-district bill, and the May report are often open at the same time. We keep all three on the same closed month, and we do not wait for April to discover which one was late.
Read the close
A month is finished when the bank and the books name the same cash, and not a day before. The report comes from that month.
Payday on your service
The company keeps its own payday service. Our setup puts wages and the owner draw into the month you approve.
After the Saturday roar
A Saturday at that stadium can still rearrange the week. We give the weekend card batch a category on Monday, roar or no roar.
The East 11th line
Texans know what a morning on East 11th costs. We still want that Saturday named in the week's sales before the month leaves the table.
Read how a month ends
When a month can leave the table
We call a month finished only when the register and the bank statement name one cash figure, the card balances and the loan balances included, and every deposit from that week still has a category you would recognize in June.
Unnamed deposits stay on the open list until someone who was there can say what they were. Borrowing a category so the report looks done only hides the puzzle until the memory is worse. One honest open item beats a tidy page we cannot defend.
Each bank line arrives with a guess beside it. That guess stays a guess until it names something the company actually did. A green row is not a close. The close is a person agreeing the guess is true.
Read the payday setup
Payday stays on your service
You keep the approval on the payday service the company already pays for. We build the map, so wages, withholdings, and a draw land in the same month you approved.
A summer raise, a new hire, or a draw that changed belongs in the month it happened. Finding it in April means the months between were softer than the bank.
The service runs the payday. We do not. Our piece is the setup, the map into the books, and a check that the approved run is the run the books show.
Read the return path
April reads the months you already saw
The return is the last reading of months that already matched the bank. Estimates for the year ahead come from those months. They do not come from cutting last year's bill into four even slices.
The receipt stack, the May franchise report, and the 1099s each keep their own date. If an extension helps, we choose it while the calendar still has room.
Closed months make April shorter. Open months turn April into a dig through old weeks. We spend March on the stubborn month so April can be a reading, not a rescue.
Read the first note
Three facts in the first note
Write which month last matched the bank, whether wages already run on your service, and whether the return belongs in that same scope. From those three we can describe the first stretch. This page has not seen the year, so this page does not quote a fee.
When the real backlog is larger than the note, you hear that before anyone adds work. You can decline before a signature. The conversation can end there, with nothing hired and nothing still running.
The bank's name and the payday service's name are enough to begin. Passwords stay off the form. Give us the year in a sentence you would say out loud.
Read the letter worry
The letter on the kitchen counter
The letter is the moment the year feels personal. A sales tax notice, a franchise reminder, and an estimate question can all look like the same kind of trouble. The useful move is to lay each letter on the month it actually names.
Most of them are about a date or a category. We set the notice beside the months already closed and say which part is already answered. The part that still needs a figure gets a figure.
A letter about a month nobody closed is a project, and the reply waits until that month is honest. A signed guess is a worse outcome than a short delay.
Read the Tuesday report
A report you can finish between meetings
The report we want you to finish between two meetings names cash, names the payday you already approved, and names the single question still open. It does not need a cover.
Categories stay put from one year to the next, so this March can sit beside the prior March. When a category has to move, the move happens in the month it changed, with the reason written there.
Clean numbers are what that rhythm produces. They are a month tied to the bank, with the open question in plain words. They are not a forecast of what a lender will say.